

Current - Mobile Banking

- 47.82K Reviews
- 4.4
- Downloads
- 5,000,000+
Our take on Current - Mobile Banking from Appgk
I approached Current as a practical money app rather than as a replacement for every financial service I use. Developed by Current, it sits in the finance category and is built around two promises that matter in everyday life: getting access to pay sooner and using activity to build credit. That makes it especially interesting for someone whose main problem is timing, not a lack of budgeting apps.
My first impression was that the app makes most sense when connected to a real routine. Imagine being paid on Friday but needing groceries, transport, or a bill covered before then. In that situation, the value is not an impressive chart or a complicated planning system. The value is a smoother path from expected income to available spending money, followed by a clearer attempt to improve your credit history over time.
It is free, rated for Everyone, and available on Android from version 8.0 onward. The app has reached more than five million installs, with an average rating of 4.4 from roughly 179 thousand ratings and about 48 thousand written reviews. Those figures suggest that Current is not a niche experiment, although popularity should not be confused with being the right fit for every financial situation.
From an upcoming paycheck to an everyday spending plan
Starting with the problem you actually need to solve
The best way to evaluate Current is to begin before opening it. If your goal is simply to see all your existing bank accounts in one place, a traditional budgeting app may be more suitable. If you need a full-service bank with a broad range of products, you may also want to compare it with an established bank or credit union. Current is more focused: it aims to help eligible users manage spending, receive money earlier, and work toward better credit habits.
Best Parts of Current - Mobile Banking
Things to Keep in Mind About Current - Mobile Banking
That focus can be useful for people who live between paydays. A small delay in income can create a chain reaction: a bill arrives, a card balance rises, and the next paycheck is already committed. Current can fit into that gap as a day-to-day money tool. I would not treat early access to pay as extra income, though. It changes timing, not the total amount you earn, so the safest use is to cover planned essentials rather than expand your spending.
The second starting condition is credit. Building credit is a long-term task, and an app cannot erase missed payments or make unaffordable borrowing safe. Current is more appealing to someone who wants a structured way to begin or strengthen credit activity while handling normal purchases. It is less compelling for a person who already has excellent credit and wants advanced lending options, detailed investment research, or a large selection of account types.
News and Features Related to Current - Mobile Banking

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Setting up a workflow instead of chasing features
Once I think of Current as part of a money workflow, the setup becomes easier to judge. I would start by deciding which income belongs in the account and which regular expenses should be paid from it. That distinction matters. Moving every dollar into a new financial app immediately can make it harder to see where obligations are actually being handled.
A sensible approach is to use Current for a defined purpose at first. For example, I might direct regular spending money there while leaving rent or other major commitments in the account that already handles them. After a few cycles, I could decide whether the arrangement is reliable enough to expand. This staged approach also makes it easier to notice any delay, rejected transaction, or confusing handoff before it affects an important bill.
Don't want to read the full review?
The app’s free price lowers the barrier to trying it, but “free” should not make me careless. I would still read the terms attached to the specific services I plan to use, especially anything connected with early pay or credit. Financial products often have conditions around eligibility, timing, and account behavior, and those details matter more than the headline promise.
Following money through the app
The central flow is straightforward in concept. Money enters through an expected payment, becomes available for spending according to the service’s rules, and then leaves through ordinary purchases or planned obligations. The useful question is not just whether money appears early; it is whether that early availability helps me make a better decision.
Screenshots
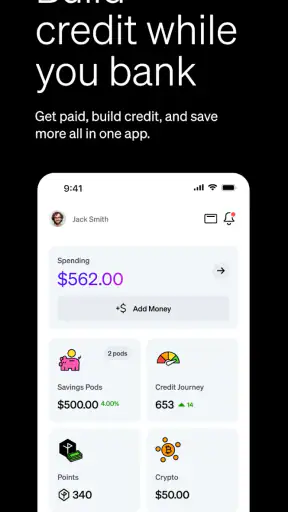
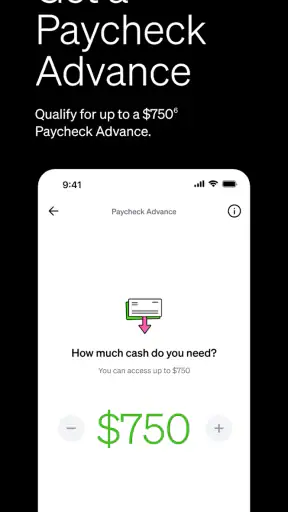
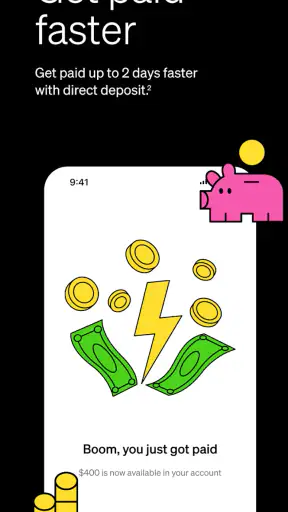
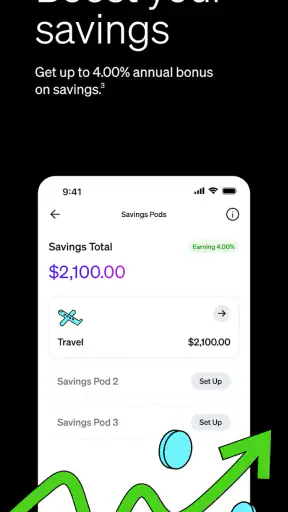
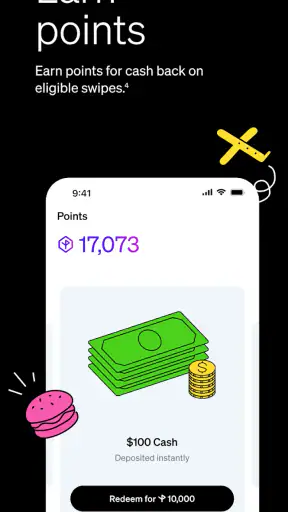
Consider a realistic weekday. I notice that my usual paycheck is due later in the week, but I need to buy groceries and refill a transit card today. If Current makes the relevant funds available early for my account, I can handle those purchases without putting them on a high-cost credit card. I would then record the spending immediately, because early access can create a false sense that I have received additional money.
This is where a simple personal rule helps: treat early pay as a timing tool, not as a reason to increase the weekly budget. I would keep a small note of what has already been accessed and what remains committed. That habit is more important than any colorful balance screen, because the main risk is spending this week’s money twice in your head.
Current also makes more sense when credit-building is treated as a separate track. Spending money and improving credit are related, but they are not the same activity. I would use the app for normal purchases I could already afford, then check how those transactions fit into my broader credit plan. The goal should be consistency and control, not creating purchases merely to generate activity.
Managing the handoffs between people and systems
Most financial friction happens at the handoffs. One handoff is between an employer or payment source and Current. Another is between Current and a merchant. A third may involve a credit-reporting process or another financial institution. When everything works, these steps feel invisible. When something is delayed or misunderstood, the app can appear responsible for a problem that began elsewhere.
For that reason, I would avoid scheduling a critical payment at the exact edge of an expected arrival. If a bill has a firm deadline, I would leave enough time for the money to move through the relevant systems and for the payment to be recognized. A service that helps me access funds earlier is valuable, but it does not remove the need to plan around processing windows.
The same caution applies when Current is only one part of my financial setup. If I use another bank for savings, an employer portal for payroll, and a separate service for a bill, I need to know which balance is authoritative for each decision. A useful routine is to check the destination before transferring money, then confirm the transaction after it posts. This sounds basic, but it prevents the common mistake of assuming that an initiated movement is already spendable.
I would also keep notifications and account records organized. When money arrives earlier than expected, an alert can be helpful, but it can also encourage impulse spending. I prefer to treat the notification as a prompt to review the plan: what is due, what is safe to spend, and what must remain untouched until the normal payday cycle catches up?
What the credit-building angle changes
The credit feature is the part that requires the most realistic expectations. A credit-building service can be useful for someone with a thin file, but the result depends on ongoing behavior and on how the service operates for the user. I would not join Current expecting an instant score transformation. The better mindset is to use it as one controlled component of a longer routine that includes paying obligations on time and avoiding balances I cannot manage.
A less obvious advantage is psychological: separating everyday spending from the temptation to borrow more can make credit goals easier to follow. If the app helps me see available money and credit-related activity in the same workflow, I can make a purchase decision with both short-term affordability and long-term consequences in mind. That does not replace reading account terms, but it can make the consequences feel less abstract.
The trade-off is that credit-building features may not be enough for users who need to repair several serious problems at once. Someone dealing with collections, identity theft, or a disputed account will likely need specialized help and direct contact with the relevant institutions. Current may support a healthier routine, but it should not be mistaken for a complete credit-repair service.
Reaching the practical result
The result I would want from Current is not merely an early balance. It is a calmer payday cycle. If the app lets me cover a planned need without resorting to expensive short-term borrowing, and if I can maintain disciplined spending while working on credit, then it has earned a place in my financial setup.
That result depends on using the app with boundaries. I would decide in advance which expenses qualify for early access, keep a record of what has been drawn forward, and review the account after each income cycle. I would also compare the convenience with the effort involved. If I constantly need to move money between services or manually reconcile balances, a conventional bank account may be simpler even if it offers fewer specialized tools.
For a person paid on a predictable schedule, Current can serve as a bridge between income and spending. For a person with irregular freelance income, the experience may require more caution. The app can be useful, but an early-pay workflow built around predictable deposits may not match income that changes from week to week. In that case, a bank with stronger cash-flow tools or a dedicated budgeting system could provide a clearer picture.
Where the workflow can break
The first weak point is timing. “Paid early” sounds simple, but real money movement involves eligibility, payment sources, processing, and merchant deadlines. I would never use an early-pay expectation as the only plan for rent, utilities, or another payment with serious consequences. Keeping a buffer is still necessary.
The second weak point is behavioral. Accessing money sooner can help avoid a costly card purchase, but it can also make spending feel less constrained. Users who already struggle with impulse purchases should be especially careful. Current may make funds easier to reach, while a traditional account with fewer immediate prompts might create a healthier pause.
The third is scope. Current is not the same as a full budgeting platform, a conventional branch-based bank, or an investment account. If I need detailed category analysis, complex household planning, business banking, or extensive financial products, I would compare alternatives before making Current my primary service. Its focused design is a strength for the right problem and a limitation for a broader one.
There is also a practical learning curve around handoffs. A transfer can be initiated but not yet usable, a payment can be authorized but not fully settled, and an expected deposit can be affected by circumstances outside the app. I would keep important records and verify final balances instead of relying on a single screen to tell the whole story.
Who should use it and who should skip it
I can recommend Current to someone who wants a free finance app centered on earlier access to pay and a more deliberate path toward building credit. It is a particularly reasonable option for a person who has predictable income, needs help smoothing the days before payday, and is willing to monitor spending rather than treat available funds as unlimited.
I would suggest looking elsewhere if you want a traditional bank relationship, extensive savings and investment choices, or a highly detailed household budgeting system. I would also be cautious if your income is unpredictable, your bills leave no margin for timing changes, or you are likely to spend early access before the original payday arrives.
The app is available on Android and its current version is 8.15.0. Its Everyone rating makes it broadly approachable, but age suitability does not remove the need for financial judgment. I would still review each service’s terms, confirm how it fits with my existing accounts, and test the workflow with a noncritical expense before depending on it for an essential payment.
My final take after following the full money journey
Current works best when I give it a narrow, useful job: receive or manage expected income, handle planned spending, and support a patient credit-building routine. The experience is less about replacing every financial tool and more about improving the handoff between getting paid and making it to the next payday without unnecessary borrowing.
The key is to use early access as a timing advantage, never as extra income. With that rule in place, the app’s strongest ideas become easier to appreciate. I can see why Current has attracted a large audience and maintained a 4.4 average, while still recognizing that convenience does not solve every banking problem.
My recommendation is therefore positive but conditional. If your main challenge is cash-flow timing and you want a focused route toward credit activity, Current is worth trying. If your priority is maximum banking breadth or deep financial analysis, a conventional alternative may serve you better. Used with a buffer, a spending plan, and careful attention to handoffs, Current can turn a stressful gap before payday into a more manageable part of the month.
Current - Mobile Banking FAQ
What is Current - Mobile Banking, and what can I use it for?
Current is a mobile banking app designed to help users manage everyday spending, receive direct deposits, transfer money, pay bills, and monitor their finances from a smartphone. After setting up an account, you can typically access a debit card, view transactions, organize spending, and use additional money-management tools. Available services and features may depend on your location, eligibility, and the account plan offered.
Is Current a real bank, and is my money protected?
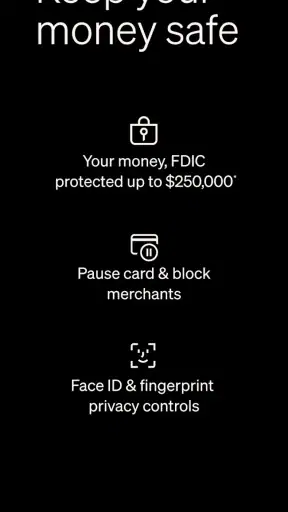
Current is a financial technology platform, while banking services are provided through partner banks rather than by the app itself in every case. Eligible funds may receive FDIC insurance through the applicable partner bank, subject to legal limits and account requirements. Before depositing money, review the current terms, disclosures, and insurance information in the app or on Current’s official website, since coverage and program details can change.
Does Current charge monthly fees or other account fees?
Current may offer access to basic banking features without a traditional monthly maintenance fee, but users should not assume that every service is free. Fees can apply to certain transactions, expedited services, cash deposits, out-of-network ATM use, overdraft-related features, or optional plans. The exact pricing depends on the product and account type, so check the fee schedule before using features that involve cash or transfers.
How do I add money to a Current account and access my funds?
You can generally fund a Current account through methods such as direct deposit, bank transfers, eligible debit-card transfers, mobile check deposit, or supported cash-deposit locations. Processing times and limits vary by method, and some options may not be available to every user. Once funds are available, you can usually spend with the Current debit card, withdraw cash at supported ATMs, or transfer money according to the account rules.
Is Current safe to use, and what should I do if I lose my phone or card?
Current uses common security measures such as account authentication, transaction alerts, card controls, and the ability to lock a card from within the app. Nevertheless, users should enable device security, choose a strong password, avoid sharing verification codes, and monitor account activity regularly. If your phone or card is lost, immediately secure your account, lock the card, and contact Current support through official channels.











